Florida Surplus Lines Tax: The Hidden Overhead Cost in Job-Specific Insurance (2026)

By Tammy Hoang, QuickBooks ProAdvisor — Construction Bookkeeping Specialist | Construction Cost Accounting
(949) 889-3283 | constructioncostaccounting.com

Job-specific insurance — builder's risk, project-specific liability, performance bonds — is a real direct overhead cost every contractor needs to price into a bid. In Florida, a meaningful share of this coverage is placed in the surplus lines market rather than the standard admitted market, which adds a real, additional tax and fee stack on top of the premium itself. Construction bookkeeping for a Florida contractor needs to capture this stack accurately, not just the base premium.
This guide covers Florida's surplus lines tax structure and what construction cost accounting should track for job-specific insurance placed in this market. This is general information — confirm current rates and requirements with the Florida Surplus Lines Service Office and your insurance agent.
1. Why Florida Job-Specific Insurance Often Lands in Surplus Lines

Florida's well-documented property insurance capacity constraints mean many contractors can't find builder's risk, project-specific liability, or other job-specific coverage in the standard admitted market — and Florida law generally requires a documented declination from admitted carriers before a risk can be placed in the surplus lines market instead.
THE REAL COST STACK ON A FLORIDA SURPLUS LINES POLICY
Confirm current rates and fees with the Florida Surplus Lines Service Office before finalizing a bid
Surplus lines premium tax | A tax of approximately 4.94 percent applied to surplus lines premium, collected through the Florida Surplus Lines Service Office (FSLSO) |
FSLSO service fee | A service fee applied to gross premium, reduced from 0.06 percent to 0.03 percent effective July 1, 2026 |
EMPA surcharge | A flat Emergency Management Preparedness Act surcharge applied per policy at inception, higher for commercial lines than personal lines |
Diligent search requirement | Florida law generally requires documented declinations from the admitted insurance market before a risk can be placed in the surplus lines market |
Source: Florida Statute § 626.913 et seq.; Florida Surplus Lines Service Office (FSLSO). Construction Cost Accounting | constructioncostaccounting.com
⚠ RED FLAG: The surplus lines tax, FSLSO service fee, and EMPA surcharge are calculated on top of the base premium, not included in it. A bid that budgets only the quoted premium amount for a Florida job-specific policy placed in the surplus lines market is understating the real insurance cost — confirm the full cost stack with your insurance agent before finalizing a price. |
2. Tracking the Full Cost Stack, Not Just the Premium
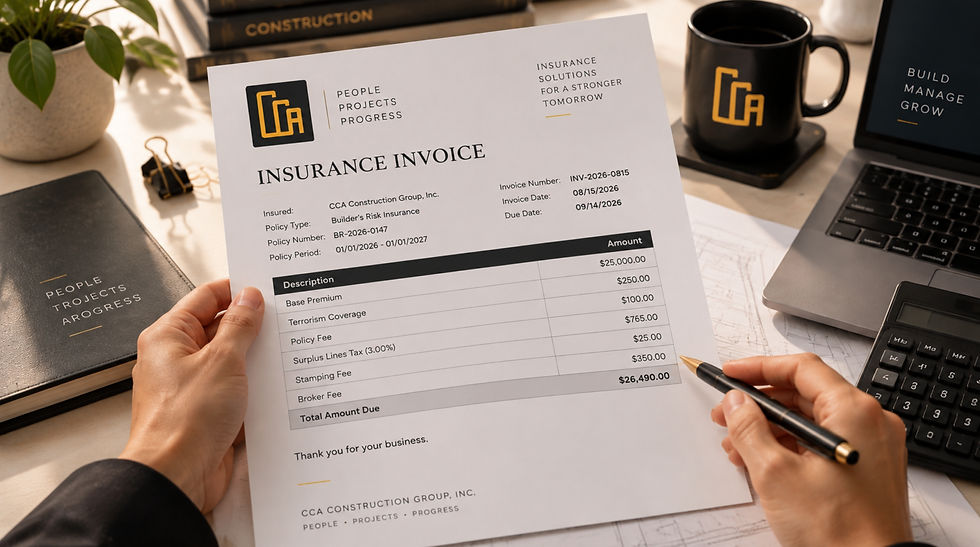
Because the surplus lines tax, service fee, and EMPA surcharge are itemized separately from the base premium, construction bookkeeping for a Florida contractor should track the full cost stack as one line item per policy, not just the premium. This is the difference between a job-specific insurance cost that's accurately priced into a bid and one that quietly erodes margin after the fact.
OWNER'S TAKEAWAY: When a job-specific policy is placed in Florida's surplus lines market, track the full cost — premium plus surplus lines tax, FSLSO service fee, and any EMPA surcharge — as one line item in your bid. Pricing off the premium alone understates the real cost every time. |
Are You Pricing the Full Surplus Lines Cost Stack Into Your Bids?
Many Florida contractors budget only the quoted premium for builder's risk or project-specific policies and miss the real tax and fee stack on top. CCA builds bookkeeping that captures the full cost. In a free 30-minute review, we'll show you where your numbers stand.
constructioncostaccounting.com | (949) 889-3283
3. Direct Versus Indirect: Where This Cost Actually Belongs

Job-specific insurance placed for a single project — including any surplus lines tax and fees tied to that specific policy — is a direct overhead cost allocated to that job, distinct from the general liability insurance a business carries indirectly across all its work. Construction cost accounting should keep this distinction clear, since misclassifying a project-specific surplus lines policy as general overhead spreads a real, job-specific cost across the wrong jobs.
The tax and fees on a Florida surplus lines policy aren't a rounding error — they're a real, calculable cost that belongs on the specific job the policy covers, not blended into general overhead where it disappears from that job's true numbers. |
4. The Reports a Florida Contractor Needs
Pulling this together, here's what a Florida contractor placing job-specific insurance in the surplus lines market should track:
Full cost stack by policy — premium plus surplus lines tax, FSLSO fee, and EMPA surcharge as one tracked total
Direct cost allocation — surplus lines policy costs tracked to the specific job, not blended into general overhead
Diligent search documentation — admitted-market declinations retained per policy
Job cost reports — actual cost versus bid, by job
With those in place, a Florida contractor prices job-specific insurance accurately and keeps this real cost attributed to the correct job. That's construction accounting doing its job in a market where this cost stack is a genuine, distinct factor.
Where Construction Cost Accounting Fits In

Construction Cost Accounting provides construction bookkeeping services for Florida contractors navigating job-specific insurance placed in the surplus lines market. For this kind of cost, that means:
Full cost stack captured — premium, tax, service fee, and surcharge tracked together, not just the premium
Direct cost allocation done correctly — project-specific policies attributed to the right job
Bid pricing that reflects the real cost — no surprise margin erosion from an underpriced insurance line
A construction bookkeeper who knows Florida — construction bookkeeping services built for the state's real insurance cost environment
We work with contractors throughout Florida who need job-specific insurance costs — including the real surplus lines tax and fee stack — tracked and allocated with precision. Our construction bookkeeper team — experienced in construction accounting for Florida's real insurance market — keeps every job's true insurance cost visible — so bids reflect the complete number, not just the premium quote. That's results-based construction bookkeeping for Florida contractors.
Price the Full Insurance Cost Stack Into Every Bid
CCA builds construction bookkeeping for Florida contractors around full surplus lines cost tracking and correct direct-cost allocation. Book a free 30-minute review and see where your books stand.
constructioncostaccounting.com | (949) 889-3283
Florida's surplus lines tax structure adds a real, calculable cost on top of the premium for job-specific insurance placed in that market — a cost most generic overhead guidance never mentions. Track the full cost stack per policy, allocate it as a direct cost to the correct job, and confirm current rates and fees with the Florida Surplus Lines Service Office before finalizing a bid.
The Florida contractors who price job-specific insurance accurately aren't budgeting the premium alone — they're the ones whose construction bookkeeping services capture the full, real cost stack. For our full service, visit our construction bookkeeping page. CCA's construction bookkeeper team and construction accounting expertise give Florida contractors that foundation. Good bookkeeping for a Florida contractor starts with pricing insurance at its true, complete cost — not just the number on the premium line.


Comments